
 Trading Trainer - 6 Percent Protocol
 Simplertrading - ‘Take The Money & Run’ Method For Faster Account Growth for Any Account Size ( PRO PACKAGE )
 Newtraderuniversity - Price Action Trading 101
 Surjeetkakkar - POS+ English 30 Days Subscription
 ITPM - Emergency Room
 Simplertrading - The Unbalanced Butterfly Strategy Class: Tilt Odds in Your Favor with this ‘High Probability Lotto Ticket’
 Momentum Stock Options Workshop - Reeds Trader
 Elliottwave - How to Trade the Highest Probability Opportunities - Price Bars and Chart Patterns
 Cameron Fous – IKNK Traders Accelerator
 Stockcyclesforecast - Gann Astro Vol III - Advanced Astrology - Horoscopes and Trading Methods
 Basecamptrading - Naked Trading Mastery
 Udemy - Python para Data Science e Machine Learning – COMPLETO
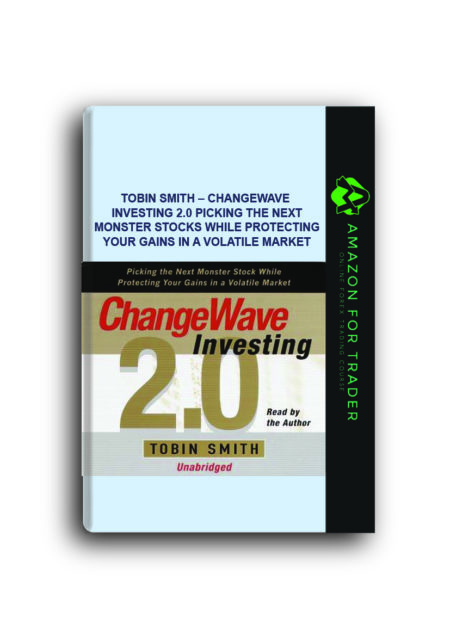 Tobin Smith – ChangeWave Investing 2.0 Picking the Next Monster Stocks While Protecting Your Gains in a Volatile Market
 SIMPLERTRADING – VOODOO LINES INDICATOR
 JIGSAW TOOLS WITH AUCTION VISTA HEATMAP V5.3F (MAY 2016)
 Stockcyclesforecast - Stock Trading Using Planetary Cycles - The Gann Method Volume II
 Hans Hannula - The Chaos Course. Cash in on Chaos
 Credit Spread Plan to Generate 5% Weekly - Sheridanmentoring
 Simplertrading - The Ultimate Spread Strategy: How to Get Paid to Earn High Premium Profits With Henry Gambell ( ELITE PACKAGE )
 PDS Trader - Option Insanity Strategy
 Udemy - Angular 7 Security Masterclass (With FREE E-Book)
 Elliottwave - How to Trade the Highest Probability Opportunities - Price Gaps
Robert J.Elliott – Mathematics of Financial Markets (2nd Ed.)
Size: 2 MB
[center][b]Get Download Links Free[/b]:
https://my.pcloud.com/publink/show?code=kZPdcSZIx9vmaMqhek7RVpIhLmCFRwBpPDk
[/center]
Product Description
Robert J.Elliott – Mathematics of Financial Markets (2nd Ed.)
This book presents the mathematics that underpins pricing models for derivative securities in modern financial markets, such as options, futures and swaps. This new edition adds substantial material from current areas of active research, such as coherent risk measures with applications to hedging, the arbitrage interval for incomplete discrete-time markets, and risk and return and sensitivity analysis for the Black-Scholes model.
Review
From the reviews:
“…This book is a valuable addition to a graduate student’s reference collection. The number of textbooks in mathematical finance is increasing much faster than the number of revolutionary contributions to the field, but this text stands above the crowd.” SIAM Review, December 2005
From the reviews of the second edition:
“The book is very carefully formatted. … this book is a valuable addition to a graduate student’s reference collection. The number of textbooks in mathematical finance is increasing much faster than the number of revolutionary contributions to the field, but this text stands above the crowd.” (Alexandre D’Aspremont, SIAM Reviews, December, 2005)
“The emphasis of the first edition of this book was on developing the mathematical concepts for the rapidly expanding field of mathematical finance. This second edition contains a significant number of changes and additions … . The target audience is readers with sound mathematical background on elementary concepts from measure-theoretic probability … . It should be an equally valuable resource to practitioners interested in the mathematical tools … . will be a very useful addition to any scholarly library.” (Theofanis Sapatinas, Journal of Applied Sciences, Vol. 32 (6), 2005)
“The second edition adds new matieral from current active research areas. A new chapter on coherent risk measures for instance reflects the recent trend in research and applications in the area of risk management. In summary, this is an excellent textbook in mathematical finance, and I can definitely recommend it.” (S. Peng, Short Book Reviews of the ISI, June 2006)
From the Back Cover
This book presents the mathematics that underpins pricing models for derivative securities, such as options, futures and swaps, in modern financial markets. The idealized continuous-time models built upon the famous Black-Scholes theory require sophisticated mathematical tools drawn from modern stochastic calculus. However, many of the underlying ideas can be explained more simply within a discrete-time framework. This is developed extensively in this substantially revised second edition to motivate the technically more demanding continuous-time theory, which includes a detailed analysis of the Black-Scholes model and its generalizations, American put options, term structure models and consumption-investment problems. The mathematics of martingales and stochastic calculus is developed where it is needed.
The new edition adds substantial material from current areas of active research, notably:
a new chapter on coherent risk measures, with applications to hedging
a complete proof of the first fundamental theorem of asset pricing for general discrete market models
the arbitrage interval for incomplete discrete-time markets
characterization of complete discrete-time markets, using extended models
risk and return and sensitivity analysis for the Black-Scholes model
The treatment remains careful and detailed rather than comprehensive, with a clear focus on options. From here the reader can progress to the current research literature and the use of similar methods for more exotic financial instruments.
The text should prove useful to graduates with a sound mathematical background, ideally a knowledge of elementary concepts from measure-theoretic probability, who wish to understand the mathematical models on which the bewildering multitude of current financial instruments used in derivative markets and credit institutions is based. The first edition has been used successfully in a wide range of Master’s programs in mathematical finance and this new edition should prove even more popular in this expanding market. It should equally be useful to risk managers and practitioners looking to master the mathematical tools needed for modern pricing and hedging techniques.
Robert J. Elliott is RBC Financial Group Professor of Finance at the Haskayne School of Business at the University of Calgary, having held positions in mathematics at the University of Alberta, Hull, Oxford, Warwick, and Northwestern. He is the author of over 300 research papers and several books, including Stochastic Calculus and Applications, Hidden Markov Models (with Lahkdar Aggoun and John Moore) and, with Lakhdar Aggoun, Measure Theory and Filtering: Theory and Applications. He is an Associate Editor of Mathematical Finance, Stochastics and Stochastics Reports, Stochastic Analysis and Applications and the Canadian Applied Mathematics Quarterly. P. Ekkehard Kopp is Professor of Mathematics, and a former Pro-Vice-Chancellor, at the University of Hull. He is the author of Martingales and Stochastic Integrals, Analysis and, with Marek Capinski, of Measure, Integral and Probability. He is a member of the Editorial Board of Springer Finance.