
Description
A hybrid strategy that combines a long-term trend-following approach with a short-term mean reversion component. Backtested on both SPY and QQQ ETFs, with a stronger equity curve for SPY. Trades are entered at the close (or optionally the next open for slightly better results).
- 237 trades
- 1.8% average gain per trade
- 51% win rate
- Profit factor: 3.2
- 14% annual return (CAGR)
- 79% market exposure
- Risk-adjusted return: 17%
- Max drawdown: -50% (SPY: -21%)
You’ll get the full trading rules – ready to test and validate.
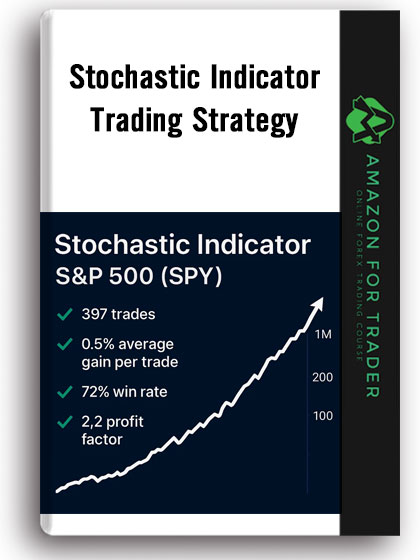
The Stochastic Oscillator is a widely used technical indicator that measures a closing price relative to its recent high-low range. This study examines whether a simple Stochastic-based strategy can generate profitable trading opportunities on the SPY ETF.
Trading Rules
The strategy was backtested on SPY from February 1993 to September 2026 using the following rules:
- Entry: Buy at the close when the 7-day Slow Stochastic %K, smoothed over three bars, falls below 25.
- Exit: Sell at the close when the current closing price rises above the previous day’s high.
- Position management: Long-only, with one open position at a time and no stop-loss or profit target.
Backtest Results
The strategy generated 394 completed trades, with a 77.7% win rate, a profit factor of 2.58, and an average gain of 0.68% per trade before commissions and slippage.
Tests of nearby lookback periods, ranging from four to twelve days, remained profitable, as did several alternative exit methods. When trades were executed at the next session’s open, the strategy maintained a 73.6% win rate and a 2.47 profit factor.
Performance remained positive across three historical market periods, although results weakened somewhat in the most recent period.
Conclusion
The backtest suggests that the Stochastic Oscillator may help identify short-term trading opportunities on SPY under these specific rules. Results remained encouraging across different parameters and execution assumptions, but the strategy is based on historical data and may be affected by transaction costs, slippage, and overfitting. Past performance does not guarantee future results.
About the salepage
Quantified Strategies is a trading and investment research platform founded in 2012 by experienced traders Oddmund Groette and Håkan Samuelsson. The platform focuses on evidence-based market research, backtested trading strategies, and systematic investing. Through historical data, statistical analysis, and practical educational resources, it helps traders make more informed decisions and develop disciplined, data-driven trading approaches.
Stochastic Indicator Trading Strategy, S&P 500, Quantified Strategies, Download S&P 500, Free S&P 500, S&P 500 Torrent, S&P 500 Review, S&P 500 Groupbuy, Download Quantified Strategies, Free Quantified Strategies, Quantified Strategies Torrent, Quantified Strategies Review, Quantified Strategies Groupbuy.